18% GST calculator: ready table
18% is the standard rate: mobiles, chargers, make-up, detergent, paint, auto parts, furniture, and clothes or shoes above ₹2,500 a piece. Add it to a price before GST, or find the GST already inside a total.
| Amount | GST to add (18%) | Total with GST | GST inside, if the amount includes 18% | Price without GST |
|---|---|---|---|---|
| ₹100 | ₹18.00 | ₹118.00 | ₹15.25 | ₹84.75 |
| ₹500 | ₹90.00 | ₹590.00 | ₹76.27 | ₹423.73 |
| ₹1,000 | ₹180.00 | ₹1,180.00 | ₹152.54 | ₹847.46 |
| ₹2,500 | ₹450.00 | ₹2,950.00 | ₹381.36 | ₹2,118.64 |
| ₹5,000 | ₹900.00 | ₹5,900.00 | ₹762.71 | ₹4,237.29 |
| ₹10,000 | ₹1,800.00 | ₹11,800.00 | ₹1,525.42 | ₹8,474.58 |
| ₹25,000 | ₹4,500.00 | ₹29,500.00 | ₹3,813.56 | ₹21,186.44 |
| ₹1,00,000 | ₹18,000.00 | ₹1,18,000.00 | ₹15,254.24 | ₹84,745.76 |
5% and 40% GST on common amounts
| Amount before GST | GST 5% | Total at 5% | GST 40% | Total at 40% |
|---|---|---|---|---|
| ₹100 | ₹5.00 | ₹105.00 | ₹40.00 | ₹140.00 |
| ₹500 | ₹25.00 | ₹525.00 | ₹200.00 | ₹700.00 |
| ₹1,000 | ₹50.00 | ₹1,050.00 | ₹400.00 | ₹1,400.00 |
| ₹2,500 | ₹125.00 | ₹2,625.00 | ₹1,000.00 | ₹3,500.00 |
| ₹5,000 | ₹250.00 | ₹5,250.00 | ₹2,000.00 | ₹7,000.00 |
| ₹10,000 | ₹500.00 | ₹10,500.00 | ₹4,000.00 | ₹14,000.00 |
| ₹25,000 | ₹1,250.00 | ₹26,250.00 | ₹10,000.00 | ₹35,000.00 |
| ₹1,00,000 | ₹5,000.00 | ₹1,05,000.00 | ₹40,000.00 | ₹1,40,000.00 |
New GST rates 2025: the slabs for goods
From 22 September 2025 the GST Council folded the old 12% and 28% slabs into 5% and 18%, and put a short list of goods at 40%. Pan masala and tobacco kept their old 28% + cess until 31 January 2026 and moved to 40% (bidi 18%) on 1 February 2026, so no goods are taxed at 12% or 28% any more.
| GST rate | What is in it (examples) |
|---|---|
| 0% | Loose rice, atta and dal, fresh and UHT milk, packed paneer, plain bread, roti, chapati and paratha, exercise books, notebooks and pencils |
| 5% | Most food and daily-use goods: packed atta, rice and dal, sugar, edible oil, tea, biscuits, cakes, namkeen, mithai, chocolates, ice cream, butter and ghee; soap bars, toothpaste, shampoo, hair oil; clothes and footwear up to ₹2,500 a piece / pair; fabric; medicines; bicycles |
| 18% | The standard rate: clothes and footwear above ₹2,500, mobile phones, chargers and earphones, TVs and ACs, make-up and perfume, detergent, paint, auto parts, watches, furniture, and anything not listed elsewhere |
| 40% | Aerated, sweetened, flavoured and caffeinated drinks (cola, soda, fizzy fruit drinks, energy drinks; not-fizzy fruit-pulp drinks like Frooti or Maaza are 5%), bigger cars, motorcycles above 350 cc; since 1 Feb 2026 also pan masala, cigarettes and tobacco (bidi 18%) |
| 3% | Gold, silver, gold and silver jewellery, imitation jewellery, pearls |
| 1.5% | Cut and polished diamonds |
| 0.25% | Rough diamonds, loose precious and semi-precious stones |
Services have their own list. Two that shops ask about: a standalone restaurant, cafe or tea stall pays 5% without input tax credit (the 56th Council confirmed it can’t choose 18%), and salons, barbers, gyms and yoga centres moved from 18% to 5% without input tax credit.
Which GST rate for my item? Shop goods table
Rates by HSN for the goods small shops sell most. For clothes and footwear the rate depends on the price of one piece or pair after discount and without GST.
| Item | HSN | GST now | Before 22 Sep 2025 |
|---|---|---|---|
| Clothing | |||
| Readymade clothes, up to ₹2,500 a piece | 61, 62 | 5% | 5% up to ₹1,000, 12% above |
| Readymade clothes, above ₹2,500 a piece | 61, 62 | 18% | 12% |
| Fabric, dress material, most sarees (any price) | 50–55 | 5% | same |
| Footwear | |||
| Footwear, up to ₹2,500 a pair | 64 | 5% | 12% up to ₹1,000, 18% above |
| Footwear, above ₹2,500 a pair | 64 | 18% | same |
| Bakery and sweets | |||
| Cakes, pastries, biscuits | 1905 | 5% | 18% |
| Plain bread; roti, chapati, paratha | 1905, 2106 | 0% | bread 0%, roti 5%, paratha 18% |
| Namkeen, bhujia; mithai | 2106 | 5% | namkeen 12% |
| Kirana / general store | |||
| Rice, atta, dal sold loose | 1006, 1101, 0713 | 0% | same |
| Rice, atta, dal, pre-packed and labelled (up to 25 kg) | 1006, 1101, 0713 | 5% | same |
| Sugar, edible oil, tea | 1701, 1507–1515, 0902 | 5% | same |
| Bath soap bars, toothpaste, shampoo, hair oil | 3401, 3306, 3305 | 5% | 18% |
| Detergent powder and liquid | 3402 | 18% | same |
| Cold drinks and water | |||
| Aerated / carbonated cold drinks with sugar or flavour (cola, soda, fizzy fruit drinks), energy drinks | 2202 | 40% | 28% + 12% cess |
| Fruit-pulp or fruit-juice drinks, not fizzy (e.g. Frooti, Maaza) | 2202 99 20 | 5% | 12% |
| Packaged drinking water (no sugar, no flavour) | 2201 | 5% | 18% (20 L jar 12%) |
| Mobile shop | |||
| Mobile phones | 8517 | 18% | same |
| Chargers, earphones, speakers, power banks | 8504, 8518, 8507 | 18% | same |
| Cosmetics and jewellery | |||
| Make-up, face cream, perfume | 3303, 3304 | 18% | same |
| Talcum powder, face powder | 3304 | 5% | 18% |
| Imitation (artificial) jewellery; gold and silver jewellery | 7117, 7113 | 3% | same |
| Other shops | |||
| Watches; sunglasses | 9102, 9004 | 18% | same |
| Spectacles (to correct vision) | 9004 | 5% | 12% |
| Exercise books, notebooks, pencils | 4820, 9609 | 0% | 12% |
| Car and bike parts | 8708, 8714 | 18% | 28% |
| Paint; furniture (not bamboo or cane) | 3208, 3209, 9403 | 18% | same |
| Pan masala, cigarettes, tobacco (bidi 18%) | 2106 90 20, 24 | 40% (from 1 Feb 2026) | 28% + cess |
| Services | |||
| Restaurant, cafe or tea stall serving food (standalone) | 9963 | 5% (no input tax credit) | same |
| Salon, barber, beauty parlour, gym, yoga | 9997 | 5% (no input tax credit) | 18% |
GST formulas with examples
- Add GST: GST = price × rate ÷ 100. ₹2,000 at 5% = ₹100; total ₹2,100.
- Total with GST: price × (100 + rate) ÷ 100. ₹2,000 × 1.05 = ₹2,100.
- GST inside an MRP: MRP × rate ÷ (100 + rate). ₹999 at 5% = ₹47.57; price without GST ₹951.43.
- Price without GST from an MRP: MRP × 100 ÷ (100 + rate), or MRP ÷ 1.05 / 1.18 / 1.40.
- CGST and SGST: half each. IGST (another state): the full rate.
Three mistakes that cost shops money
- Taking 18% of a GST-inclusive total. 18% of ₹1,180 is ₹212.40, but the GST inside is ₹180. Divide by 118, not 100.
- Taking GST off before the discount. A discount shown on the bill comes off first; GST is charged on what is left (₹1,000 − ₹100 = ₹900, then 5% = ₹45).
- Using one rate for the whole bill. Each item has its own rate: a kirana bill can have 0% loose atta, 5% biscuits and 18% detergent; a clothing bill can have a 5% kurta and an 18% lehenga.
CGST + SGST or IGST?
| Sale | Tax on the bill | ₹1,000 at 18% |
|---|---|---|
| Customer in your own state (every counter sale) | CGST + SGST, half each | ₹90.00 + ₹90.00 |
| Goods sent to a buyer in another state | IGST, the full rate | ₹180.00 |
| In a union territory without a legislature | CGST + UTGST, half each | ₹90.00 + ₹90.00 |
One bill, two rates: worked example
A customer buys a shirt, a belt and a perfume. Tags are MRP (GST included). The shirt follows the clothes rule (one piece under ₹2,500, so 5%); the belt and perfume carry their own 18%. This is how the Tap & Bill app works it out, rate group by rate group:
| Item | MRP | GST rate | Taxable value | GST inside |
|---|---|---|---|---|
| Cotton shirt (clothes rule) | ₹1,299 | 5% | ₹1,237.14 | ₹61.86 |
| Leather belt (own rate 18%) | ₹799 | 18% | ₹677.12 | ₹121.88 |
| Perfume (own rate 18%) | ₹499 | 18% | ₹422.88 | ₹76.12 |
At 5%: taxable ₹1,237.14, CGST ₹30.93 + SGST ₹30.93. At 18%: taxable ₹1,100.00, CGST ₹99.00 + SGST ₹99.00. The customer pays ₹2,597, the sum of the tags. A single 18% on the whole bill would have put ₹136.29 more GST on the shirt than the law asks, money that comes out of your margin.
Tap & Bill: the right GST on every bill, by itself
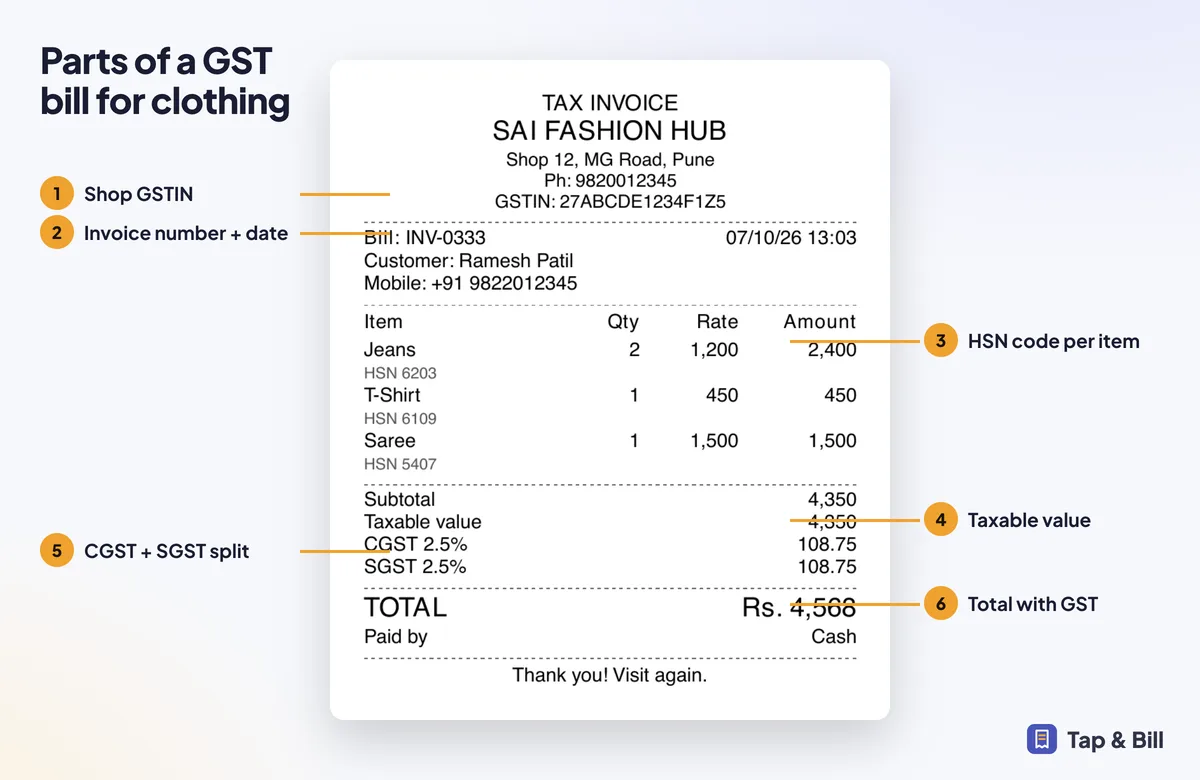
- Rate per item. Give an item or category its own rate (0%, 5%, 18% or 40%, and 3% for jewellery), on the phone or the computer, or one rate for the whole shop. A 40% line prints CGST 20% + SGST 20%.
- Clothes rule built in. Garments and footwear get 5% or 18% by the price of one piece after discount, line by line.
- MRP or + GST. Settings → GST: prices include GST (MRP tags) or GST goes on top. Discount comes off before GST.
- A proper tax invoice. GSTIN, HSN, CGST + SGST for each rate, place of supply; printed on a 58 / 80 mm thermal printer or sent on WhatsApp.
- GST report for your CA. Rate-wise, B2B and HSN summary, exported to Excel.
What it can’t do yet: bills are for sales within your state (no IGST invoices for goods sent to another state), and there is no e-invoice or e-way bill. Items still saved at the old 12% or 28% keep that rate until you change them; the rate picker shows them as “old rate”. A shop without a GSTIN makes plain bills with no GST, as the law requires.
GST bills are on every plan, including the Free plan (60 bills a month). Paid plans start at ₹199 a month (Basic), with no GST added to our price; see all plans. More on GST bills: GST billing in Tap & Bill.